Subscribe
Share
Share
Embed
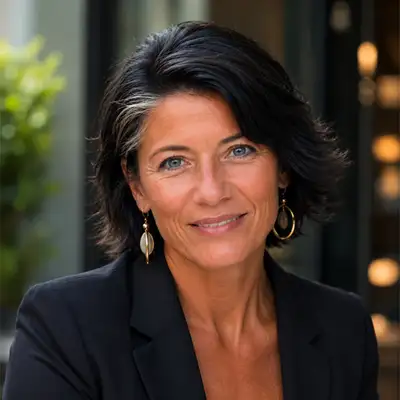
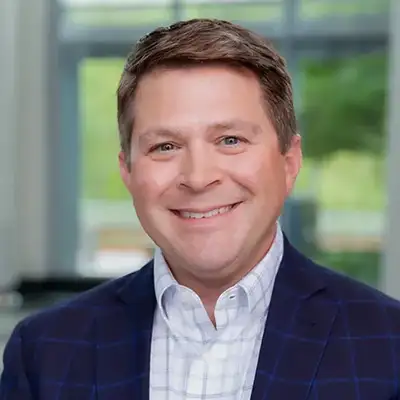
The Auto Market Brief, powered by Cox Automotive, breaks down the latest trends and forecasts shaping the automotive industry. The show is hosted by Cox Automotive Executive Analyst Erin Keating, coupling years of experience translating data and trends with the data and industry insights of the largest automotive services and technology provider.
Joined by other Cox Automotive experts and outside guests, you’ll get data-driven insights and industry outlooks from some of the industry’s leading voices.
Welcome to The Auto Market Brief from Cox Automotive. Each episode, our experts and special guests break down the latest trends, insights, and news shaping the automotive market. We'll give you the information that truly matters so you can make smarter decisions and drive your business forward. Hello. Welcome back to The Auto Market Brief.
Erin Keating:I'm Erin Keating, your host and Cox Automotive's executive analyst. And I am joined this week, as usual, with our chief economist, Jeremy Robb. Jeremy, good to see you.
Jeremy Robb:Good to see you too. Good morning.
Erin Keating:Good morning. I know we have a couple of things that have hit the airwaves this week. And certainly, Jackson Hole is dominating a lot of things in the economy right now and between today and tomorrow. So that should be interesting to hear your perspective on that. But we also got a couple of reading and a second reading on GDP, a couple of new inflation readings and used sales, I think have picked up.
Erin Keating:So you've got some information for us on used and Manheim as well. So excited to kick off talking about the bigger picture here. For me, I mean, Canada has also conquered the airwaves this week. Tariffs, shocking, have conquered the airwaves this week. So I think I'll go into a little bit of a deep dive on tariffs and just production in The US and what it all means.
Erin Keating:And of course, we have our August sales projections. So why don't we kick it off with you, Jeremy? Where do you want to start? Let's see.
Jeremy Robb:Yeah, we'll just start at the top, and I'll let you cover the topic de jure with the Canadian tariffs, which everyone has asked about all week long. But we got our second reading on GDP growth this week for 2Q, so that ended in June. It was the same at up 1.5% on an annualized basis, so no really big change. Got a little bit of a higher reading on consumer spending, up to 3.4% from 3.2, driven by health care spending a little bit more, but that was offset a little bit by some downward reads and government spending, private inventories and such, still getting a lot of a boost from the CapEx spending related to AI. And I did some other napkin math to look at, like, what GDP growth is without that, you know, nonresidential CapEx spending, and it's pretty low the last So just goes to show you, like, that is that part of the economy is really supporting a lot of things overall.
Jeremy Robb:But but, yeah, that was that. We also got some data midweek this week on personal income and spending trends, which I really kind of home in on. Because over the last few years with inflation running a little bit higher than expected, you know, people need their income growth to outpace expenses. And we were getting that trend to at least be tighter a little bit last year with inflation coming down, but this year it's picked back up. So we actually saw decent levels of gains in personal income.
Jeremy Robb:It was up 0.4% month over month. It's higher by 3.7 year over year. It's a little bit lower than last month, but still good growth. Personal spending actually slowed for the second month in a row, up just 0.2% month over month. But that still means that on a year over year basis, we've got higher growth in expenses versus income.
Jeremy Robb:So, you know, that can that can hurt. If we adjust for inflation, real personal expenditures, which a lot of people track, were steady or actually showed no change in July. So so that was good, and we got a little bit of a rebound in personal savings. All in, those metrics, a little bit better. Yeah.
Jeremy Robb:Enjoy. So good to see. And then we also got the reading for PCE inflation, which the Fed Fed covers
Erin Keating:Sure.
Jeremy Robb:For July as well. And that came in a little bit hotter on a month over month, year over year basis overall versus what the market expected. Year over year is up 3.7. The market thought it would be like 3.6. But core, you just take out, you know, things that that don't move around quite as much was in line with what the market expected.
Jeremy Robb:So it's a little bit better of a trend. Still, that is really highly influenced by shelter, just like the CPI is overall.
Erin Keating:Right.
Jeremy Robb:But if we look at some of the components that are more tracking closely with automotive, we see that transportation services, which includes vehicle maintenance and repair and also public transportation costs, those were up 7.1% in July. And the public transportation component of some of that has actually been, running a little bit hotter this year. So those pieces are they're not weighted as heavily in the PCE index, but it's important for us to pay attention to because it's automotive. Related. But on the vehicle prices component of that, not seeing a lot of inflation, there really.
Erin Keating:In line of what we've saying. Right? I mean, we've been saying for a while now, vehicle prices really aren't the challenges. It's really that bigger share of wallet that people have to dedicate to shelter, energy, etcetera, etcetera. Right?
Jeremy Robb:Absolutely. This is what I I was on a thing I did earlier this week and talked about it for a while. The price of the vehicle gets a lot of press. Right. Because it's a high price.
Jeremy Robb:Dollars 50,000 new car, dollars 30,000 used car, you know, those are big numbers, a lot heavy. You know, people take out loans against them, that kind of thing. But the compounding inflation of those two factors has not been moving quite as high as insurance, maintenance and repair, and things like that. And these things like tariffs starting to show up in some of the parts, maintenance and repair costs, I think, too. It's, you know, it's really hard to track the tariff impact out of that.
Jeremy Robb:But now that we've had, you know, higher tariffs for about a year, you're seeing, some of that come through.
Erin Keating:Sure. Yeah, I think that's the part about tariffs that a lot of people forget. It's not just new vehicles. Really, the broader impact truly is for every car owner in the country because of the parts.
Jeremy Robb:Absolutely. Yeah. And, you know, we've seen a little bit less supply of these older units this year, which is putting prices of older units up a little bit. But that may part of that may be because people can go work on that car and get the part and things like that. So parts, you know, and the ability to repair a vehicle, very important for consumers out there, especially as the average age of the vehicle on the road
Erin Keating:just Exactly.
Jeremy Robb:Continues to rise.
Erin Keating:Right. Exactly. And we gotta hold on to that. That nostalgia won't last forever with these software defined vehicles, but for now, it's really important. Yeah.
Jeremy Robb:Totally. Yeah. It's funny. Recently started driving a different vehicle, which is pretty common out in the marketplace. And it's like, you say this too, and we all know it.
Jeremy Robb:You start to notice how many are on the road, and, you know, it's a, like a midsize hybrid kind of car, and it's you there's everywhere. It's like every car is a midsize crossover of some type, you know, very, like, I think people seek some differentiation. I'll just put it
Erin Keating:that Yeah. Exactly right. Yep. And then you saw some stuff on the the used side, the Manheim and the wholesale and used. What's going on there?
Jeremy Robb:Yeah. I and I think this is important to bring up, obviously, you know, because Manheim's a huge part of our business. But the other reason it's important is because we saw a little bit of a slowdown in prices at Manheim and and activity in July. And in the first two weeks of August, when we put out the mid month movie release, prices had come in, they had been stronger for most of the year leading up to this point. But the past couple of weeks, we've started seeing sales conversion increase, which is how many cars are sold for how many cars are offered.
Jeremy Robb:That's a pretty good trend. And that gets more supportive of pricing. I even saw EV prices actually were up just a little bit last week on a week over week basis. So there's just some things to monitor out there. I think it's important.
Jeremy Robb:Last year, August was a really strong month for the wholesale market. That was tied to tariffs still. We had that kind of a second kick of demand out in the marketplace. So the year over year comparisons might get a little bit tough in August, but seeing a little bit more pickup at Manheim. And I think the reason why our data on retail sales is like ten days lag to that kind of thing.
Jeremy Robb:But when you look at the most recent readings, we've seen used vehicle transactions start to pick back up. And so we saw more strength in the new market in June and July. That's kind of flattish, like right now looks Okay in August. But then we've seen used, after that kind of went down maybe a little bit in July, start to pick back up on the retail side. And that's very supportive of what's happening at Manheim, right when we see that data point too.
Jeremy Robb:So just like we always say, the market is very dynamic. There are lots of pockets of demand out there from people that have put off buying those cars. And at the end of the day, it's always supportive of somebody needing to have a new vehicle transaction going on.
Erin Keating:Yeah. Amazingly enough, people in The United States still need to get from point A to point B, typically with four wheels and an engine.
Jeremy Robb:And the automotive industry and Ubers.
Erin Keating:Exactly right. Exactly right. Yeah. It's it's constantly having to remember we are a very big country with long distances. Even if you only have to travel, five miles in a city, our our public transportation is still not really there just yet to allow people to switch to some other mode of transportation.
Erin Keating:And luckily for us, that means the automotive industry will continue to be resilient and move forward. Yeah. What are you making Jackson Hole now? I mean, I know the PCE is a number that we say the Fed traditionally looks at, but we're all waiting, I guess, with bated breath to some extent to hear what Warsh has to say tomorrow. But what are your expectations coming out of that?
Jeremy Robb:Well, from what I've observed and read, people aren't expecting him to be very explicit in providing guidance around interest rate policy, maybe talk about some of his committees. They put together this task force a little bit more. And maybe he'll talk a little bit about just the overall outlook for Treasury debt markets and things like that. That's come under scrutiny a lot lately, with the national debt rising about $40,000,000,000,000 and a lot of people, a lot of big investors coming out, writing op eds in The Wall Street Journal and such about things. So it's a really important time.
Jeremy Robb:He's a new Fed chair. He's been around for a while, but not in the Fed for over a decade or so until recently. And this Jackson Hole symposium is always a pretty interesting time. August summer's over. You're going into fall, the end of the year.
Jeremy Robb:A lot of businesses are in planning cycles. I do a lot of talks for big businesses about what do we think the market's going to be and things like that. And so a lot of eyes are on Jackson Hole tomorrow. It would be nice to be there because I'm assuming it's probably pretty nice temperatures and I like cooler weather. But I'm not.
Jeremy Robb:I'll watch from the TV. But I'm very interested in what he says too. Big stage for him on his first try there. But there's just so much interest from the market overall about what's going on that it's going be a big event.
Erin Keating:Yeah, absolutely. Well, appreciate your insights as always. Anything you want to wrap us up with this week?
Jeremy Robb:No, I don't think so. I just think I told somebody else, some of the economic data we see is mildly positive. It doesn't really make you feel great, but you can't go stick your head in the sand either. And then you look at these vehicle transactions and what's going on, and you just can't get too negative. But at least at the national level, because they say that.
Jeremy Robb:I know I'm sure there are different pockets of the market that are doing a little bit differently.
Erin Keating:Right. Maybe you'd like to liken it to back to school, right? You've got jitters, not overly positive. You don't necessarily know you want to go walk the halls again, but same time you got your new outfit on, you're headed in, you wanna be a little optimistic.
Jeremy Robb:New backpack,
Erin Keating:new trap Exactly. So back to school it is. We are feeling trepidation, but also some optimism and some maybe hope that this can be stabilizing for a bit. So well, thank you, Jeremy. I appreciate it.
Erin Keating:And I look forward to seeing what comes out on Friday and, in our next discussion, seeing how that impacts things.
Jeremy Robb:It'll be here before we know it.
Erin Keating:Exactly. Thanks. Take care. Okay. So today I want to focus on what might be the most important question facing the auto industry right now, because as I mentioned in our conversation with Jeremy, there certainly were a couple of big announcements this week.
Erin Keating:But really, the big question that everyone's asking, and we have gotten a ton of this this week from the media, is are tariffs actually changing automaker behavior? Because for months, we've been talking about what tariffs might do. You know, this week, we're getting a growing list of real world examples that suggest manufacturers are making strategic decisions differently than they were a few years ago. And the question is, where does tariffs fall in the line of impact there? So the latest headline, of course, is President Trump's proposal to increase tariffs on Canadian imports, automotive parts, and automotive vehicles to 50%, putting additional pressure on one of the most integrated automotive trade relationships in the world, honestly.
Erin Keating:But I think what the more interesting story is what we're actually seeing from the automakers themselves, because this really isn't just a tariff story. The proposed 50% tariff on Canadian imports understandably has captured attention because Canada remains deeply connected to North American vehicle and parts production. But I'd argue this really isn't a story about Canada. It's actually a story about how manufacturers, period, are managing uncertainty because this continues to evolve as a story for us. A few years ago, most automakers optimized almost exclusively for efficiency.
Erin Keating:Production went wherever costs were lowest, components crossed borders multiple times, supply chains were stretched across the globe. We were truly a globalized automotive industry, and that started changing honestly before today's tariff debate. The pandemic, we can't forget, exposed major supply chain vulnerabilities. And then there was increasing geopolitical tensions, particularly around China, which really emerged as a competitor versus just an industrial capital of the world. Right?
Erin Keating:And it forced companies to think differently about concentration risk. And then we, of course, at the same time, we were dealing with mandates around electric vehicles and at least specifically for The US market where demand wasn't necessarily keeping up. So investments were happening all around us that were really requiring automakers to rethink their production, their supply chain, what they were going to do where, how they were going to regionalize activities. So tariffs didn't really create the shift in all of this, but they have certainly accelerated. We can't ignore it.
Erin Keating:And on the margins, they're absolutely impacting at a minimum announcements from most of the manufacturers. So let's talk about some of what the automakers are doing right now. Take Honda as an example. So Honda said it needs more North American capacity to support the strong hybrid demand here, and it's evaluating future production expansion. However, at the same time, their executives have very clearly come forward to say they may reconsider opening an eighth production facility here in The United States if the USMCA is not settled.
Erin Keating:So yes, the tariffs matter, but what matters more is the certainty and stabilization of the regulatory environment, including for tariffs for a company like Honda. But then there's Hyundai this week that is really pushing a much more aggressive posture. They're expanding their manufacturing footprint and launching more than 100 new or refreshed products globally over the next several years, including the entry into the body on frame trucks and commercial vehicles. So what's interesting is that that is, you know, two separate companies who are making decisions based on very different goals for their companies and for their trajectory globally. Right?
Erin Keating:Then you have Nissan's decision moving rogue production to The US. It might sound like a tariff story at first, and it probably is to some degree for sure. But it also might reflect something a little bit more practical, available capacity. We knew that the rogue plants had actually reduced production capacity for a bit there, and now they've got underutilized capacity. The Rogue is a very important vehicle for them to make a true comeback here in The US.
Erin Keating:And so today's environment really makes that decision much easier. Right? Then you have Ford's plans. We heard them talk about how Lincoln production is coming back to The US. And yes, tariffs, again, on the margins and maybe even more substantially play a part in that.
Erin Keating:But of course, any vehicle built in China also comes under scrutiny with the Connected Vehicles Act that's already in play by the Commerce Department and what's been proposed by Senator Moreno in coming into the market of, you know, where are parts manufactured and how connected are they with Chinese owned manufacturing, whether that's in the supply chain or the assembly of the vehicle itself. Then there's companies like Mercedes. You know, this presents a really interesting example because some manufacturing moves may be less about avoiding imports and more about positioning US plants as export hubs. So in other words, the goal isn't necessarily to produce fewer vehicles globally. It's where it's producing them differently.
Erin Keating:And then an interesting player in the market that came up this week, JLR. So Jaguar Land Rover. They're not a volume player like Ford, GM, Toyota, Hyundai, etcetera. But that's exactly why the Defender announcement stands out a bit. It's the first time that Jaguar or Land Rover would have manufactured vehicles here in The US, and it's a tie up with Stellantis.
Erin Keating:So it's a significant strategic shift for a company that historically has not viewed The US as a manufacturing base. So what ties all these announcements together isn't tariffs alone. It's that companies appear increasingly willing to localize production, diversify risk, and rethink manufacturing footprints. The common thread isn't necessarily politics. It isn't necessarily regulation or trade.
Erin Keating:It's really resilience, right? And so all of these are pulling at the opportunity to be resilient, but the companies seem to be making strategic decisions to make sure that they can be resilient, regardless of what those shifts and instabilities are. Meanwhile, the interesting thing is that consumers keep showing up. So Jeremy and I were talking about how spending continues even though the economy sounds like it's kind of reaching stable ground, but we know that there's underlying pressure, especially through inflation and share of wallet, etcetera, etcetera. So while the executives are out there making decisions on what could shape manufacturing through the next decade, consumers continue to focus on much simpler math questions.
Erin Keating:Can I afford the payment? Do I like the vehicle? Can I find the model I want? Right? These are all the questions of the consumer on a day to day cadence.
Erin Keating:And that's why the latest Katz Automotive forecast is worth noting. August new vehicle sales are expected to reach approximately 1,350,000 units. So that's translating to a seasonally adjusted annual rate above 16,000,000 units for the sixth consecutive month. So while volume is expected to be a little bit lower than usually, you know, we saw unusually strong pace last year, given the run up of the tax credits expiring, etcetera, and some of the tariff stories where we were seeing some pull ahead purchasing. The broader story, though, remains one of resilience.
Erin Keating:A lot of analysts continue to expect that affordability pressures and higher interest rates, the tariff uncertainty, and broader economic concerns might slow demand more dramatically. And instead, it really hasn't happened. Consumers have largely remained in the market. And that's a really important contrast for us to consider. Automakers are thinking about supply chains, localization, trade policy, capital allocation, etcetera, through 2030.
Erin Keating:And meanwhile, consumers are just mostly thinking about next month's payment and the ability to get from point A to B on four wheels with an engine. Right? So if there's one takeaway from this week, it's probably that we're asking the wrong question when we're asking about whether tariffs are working. A better question just might be, are tariffs accelerating a manufacturing and realignment that was already underway? Because when you combine lessons from the pandemic, concerns about supply chain concentration, geopolitical uncertainty, and today's trade environment, we're seeing evidence that manufacturers are making different decisions than they might have made five years ago.
Erin Keating:Not every investment announcement is a tariff story. Collectively, they're telling us something important about how automakers are preparing for a world where disruption is really just no longer the exception. It's the operating environment. So with that, we will keep an eye on what does happen with Canada. It is a deadline that is set for January, which to me says negotiations, will be underway, and we shall continue to be a source you can turn to to hear what the latest news around that is.
Erin Keating:As always, we thank you for listening to The Auto Market Brief. Be sure to like, subscribe, and share the show with your friends and colleagues. Remember to check out all of our insights and updates at coxautoinc.com, and stay tuned to the Auto Market Brief for the high notes in our economy, the headlines that matter across the industry, and more conversations that help make sense of the market. Take care. Thanks for joining us on this episode of The Auto Market Brief.
Erin Keating:To stay up to date with all the latest news and perspectives from our team of experts, be sure to visit our insights hub at coxautoinc.com.